Location
123 Business Street, Suite 456
New York, NY 10001, USA
Contact us
Location


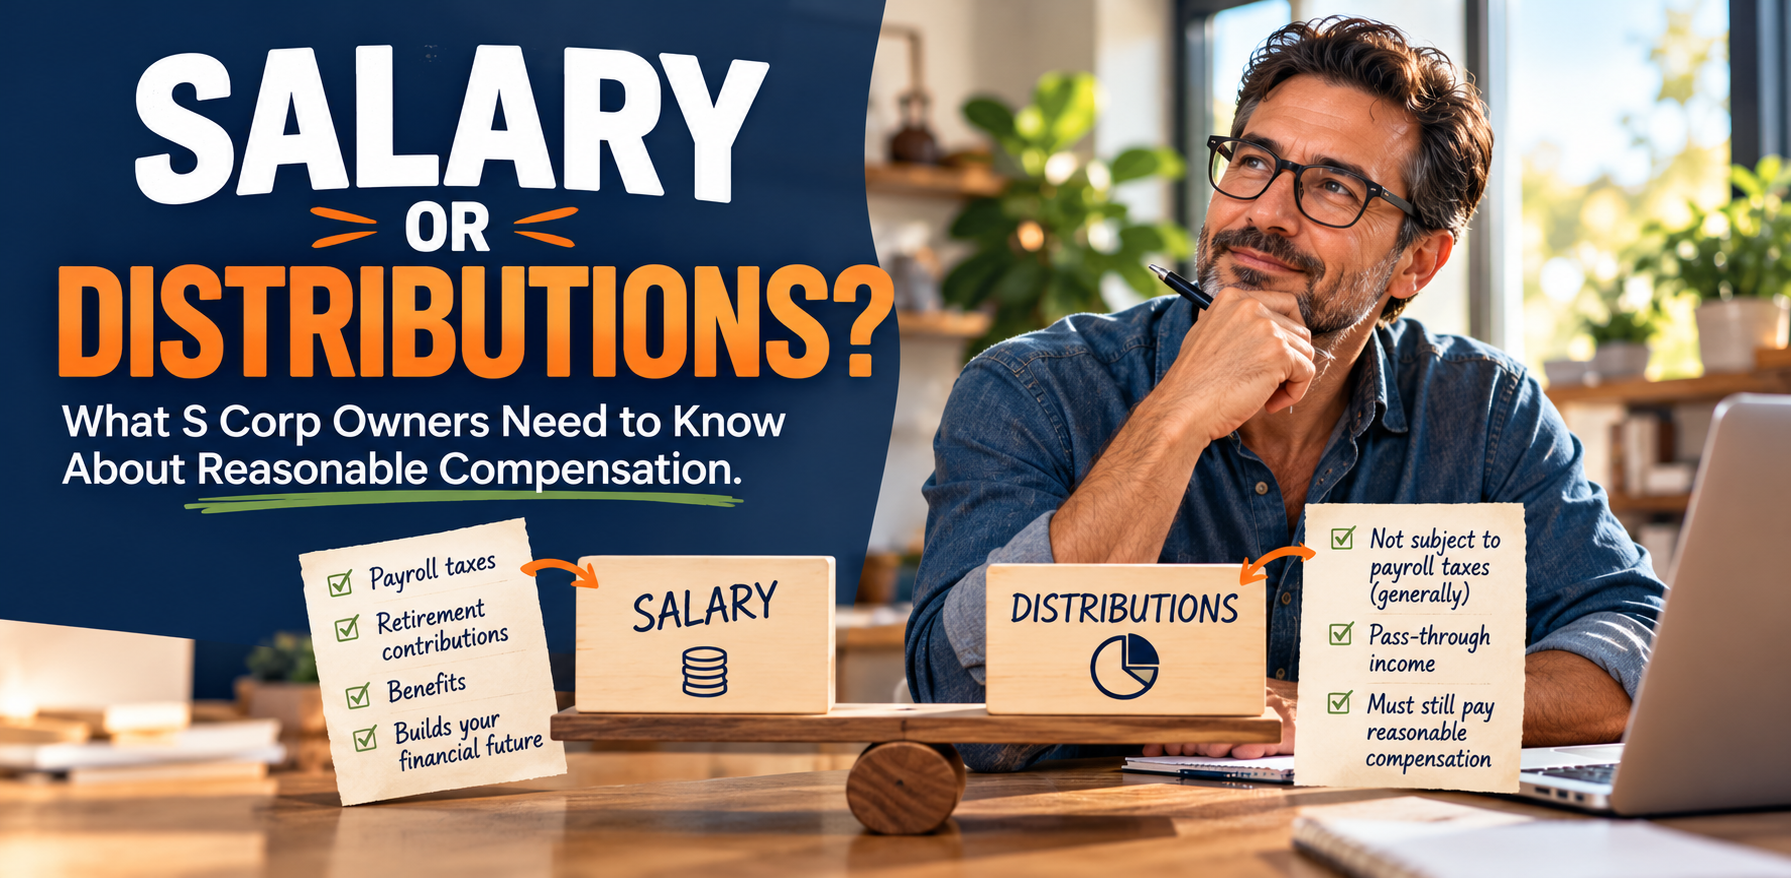
Let’s talk about your paycheck. Not your employees’ paychecks. We have spent plenty of time talking about those lately. We are talking about yours.
If you own an S corporation, there is a good chance you have heard that one of the benefits is being able to pay yourself through a combination of salary and distributions. That is true. But somewhere along the way, a lot of business owners have gotten the impression that the goal is to pay themselves the smallest salary possible and take everything else as distributions.
After all, distributions generally are not subject to Social Security and Medicare employment taxes. Sounds like a pretty good deal, right?
Well, there is a catch.
The IRS expects shareholder-employees who perform services for their S corporations to receive reasonable compensation for that work. If your salary does not reasonably reflect what you actually do for your business, you could be creating an expensive tax problem. With 2026 winding down, now is a good time to make sure you are paying yourself correctly. Pasted text
Reasonable compensation is the amount an S corporation pays a shareholder-employee for the services they provide to the business. In plain English, it is what someone would reasonably be paid to perform the work you are doing.
The IRS requires S corporations to pay reasonable compensation to shareholder-employees for their services before making nonwage distributions to them. The IRS can also reclassify distributions as wages when those payments are really compensation for work performed. Pasted text
That means being a business owner does not automatically give you the freedom to decide your work is worth $10,000 a year while taking another $150,000 in distributions. You can make that decision, of course. The IRS may just disagree with you.
There is no universal salary amount that works for every S corporation owner, and there is no IRS rule that says you must take exactly 50% of your business income as wages and 50% as distributions.
Despite what you may have heard, there is no magic percentage that makes your compensation reasonable.
Instead, the IRS considers several factors, including your training, experience, job responsibilities, time devoted to the business, and what comparable businesses pay for similar services. It also looks at the source of the company’s revenue, including how much of that revenue comes directly from the shareholder’s personal services compared with the work of other employees or the company’s capital and equipment. Pasted text
Consider two business owners. One owns a consulting company where they personally provide nearly all the services clients purchase. The other owns a manufacturing company with 30 employees, specialized equipment, and a management team handling day-to-day operations. Both businesses might generate $500,000 in annual revenue, but the owner’s contribution to that revenue looks very different.
That is why reasonable compensation is not determined by revenue alone. It is determined by the actual work being performed.
Not when those distributions are being used to replace reasonable compensation for services.
This is one of the biggest misconceptions about S corporations. Shareholder distributions and wages serve different purposes. Wages compensate an owner for the work they perform as an employee. Distributions generally represent money paid to the owner in their capacity as a shareholder.
Wages are subject to applicable payroll taxes and withholding. Nonwage S corporation distributions generally are not subject to employment taxes. But that does not mean every dollar you take out of your business can automatically be classified as a distribution. Pasted text
There is another distinction worth understanding too: distributions are not necessarily tax-free. S corporation income generally passes through to shareholders and is reported on their individual income tax returns whether or not that income is distributed. The tax treatment of a particular distribution depends on several factors, including the shareholder’s stock basis. Pasted text
So when someone says, “Just take it as a distribution and you won’t pay taxes,” they are leaving out some pretty important information.
Potentially, a rather unpleasant tax bill.
If the IRS determines that distributions should have been treated as compensation, it can reclassify those payments as wages subject to applicable employment taxes. That can create additional tax liabilities, interest, and potentially penalties.
This is not just hypothetical. The IRS references several court cases supporting its authority to reclassify S corporation payments as wages. One frequently cited case involved an accountant who paid himself $24,000 in annual wages while receiving substantially larger distributions. The court upheld the determination that his compensation was unreasonably low based on the services he provided. Pasted text
The lesson is not that $24,000 is automatically an unreasonable salary. The lesson is that your compensation needs to make sense based on your responsibilities and circumstances. A number is not reasonable simply because you decided that was what you wanted to pay yourself.
Start with a surprisingly simple question: if you were not working in your business, what would you have to pay someone else to do your job?
Most small business owners wear several hats. You might be the CEO in the morning, the sales manager after lunch, and the person troubleshooting the printer at 4:30. You might oversee employees, develop business strategy, manage client relationships, handle purchasing, and occasionally jump into the actual work when someone calls in sick.
It is unlikely that any one job title accurately describes everything you do.
A reasonable compensation review should consider your actual responsibilities, how much time you spend performing them, and what the market pays for comparable work. One business owner might spend 40% of their time delivering professional services, 25% managing employees and operations, 20% developing sales and business relationships, and 15% handling administrative work. Looking at the role that way creates a much more realistic picture of what the owner is actually doing. Pasted text
From there, compare those responsibilities with relevant compensation data. The IRS specifically identifies comparable business compensation, duties, experience, time devoted to the business, and compensation agreements as factors in evaluating reasonable pay.
The goal is not to find the lowest number you can justify. It is to develop a compensation amount that reasonably reflects the value of the services you are providing and to document how you arrived at that number.
Not necessarily, but it should be evaluated regularly.
A lot can change in a business over the course of a year. Maybe you hired a general manager who took over responsibilities you previously handled. Maybe the business expanded and you are now managing twice as many employees. Maybe you reduced your involvement and are working only part-time. Or maybe you are more involved than ever because the company is growing quickly and needs your expertise.
Any of those changes could affect what reasonable compensation looks like.
Your company’s financial performance may also be relevant, although financial results alone do not determine the appropriate salary. A practical approach is to review shareholder compensation at least annually, ideally as part of your year-end tax planning and upcoming budget process. Pasted text
If your responsibilities changed significantly during the year, though, do not wait until December to acknowledge it.
This is where things can get complicated for smaller businesses.
Not every S corporation is generating enough cash to comfortably support the owner’s compensation, especially in the early years. If your business is struggling financially, that is certainly relevant to the broader compensation conversation.
But limited cash does not automatically mean you can take distributions while paying yourself little or nothing for substantial services.
The IRS is particularly concerned when business owners receive money from the company but avoid treating payments for their work as wages. A business with limited cash and no owner distributions presents a very different situation from a profitable company regularly distributing significant amounts to an owner who receives minimal payroll compensation. Pasted text
If cash flow is tight, work with your tax advisor to evaluate the facts before making decisions about compensation or distributions. The answer should reflect the actual financial condition of the business, not simply a strategy to avoid payroll taxes.
Health insurance is another year-end item that frequently gets overlooked.
If you are a shareholder who owns more than 2% of an S corporation, special rules generally apply to health insurance premiums paid or reimbursed by the business. Under IRS guidance, qualifying premiums are generally included in the shareholder-employee’s Form W-2 wages for federal income tax purposes.
When the applicable requirements are met, those amounts generally are not subject to Social Security or Medicare taxes, and the shareholder may also qualify for a self-employed health insurance deduction on their individual return. Pasted text
The arrangement needs to be handled correctly. If your business has been paying your health insurance premiums throughout 2026, make sure your payroll and tax teams know about it before W-2s are prepared.
This is not the kind of surprise you want to discover in February.
Generally, no.
If you are an S corporation shareholder-employee participating in a company retirement plan, your retirement contributions are generally based on eligible W-2 compensation. Shareholder distributions are not considered earned income for retirement plan contribution purposes. Pasted text
That means you cannot simply take a large distribution and treat it as compensation for calculating your 401(k) contribution.
This is another reason owner compensation decisions should involve more than minimizing payroll taxes. Your salary can affect retirement planning, benefits, and other financial decisions. Sometimes what looks like a tax savings in one area creates an unintended limitation somewhere else.
If you operate an S corporation, October is a great time to review your year-to-date compensation because you still have time to make thoughtful decisions before the year ends.
Start by looking at your year-to-date wages and distributions. Ask whether your salary reasonably reflects the services you are providing and whether you have documentation to support how that salary was determined. Review any health insurance premiums paid or reimbursed by the business, confirm that retirement contributions are being calculated using eligible compensation, and look at your remaining payroll schedule to see whether any needed adjustments can still be processed correctly in 2026.
You should also look ahead to 2027. If your responsibilities, business structure, or compensation needs are likely to change next year, this is a good time to build that into your planning.
One more thing: payroll adjustments should be handled as actual payroll transactions with proper withholding, reporting, and deposits. Do not assume you can simply make a journal entry in December and call something wages. The original draft specifically notes that W-2 reporting is generally based on when wages are paid, so if corrections are needed, involve your payroll and tax professionals before the year closes. Pasted text
Reasonable compensation is not just a compliance obligation. It is part of your broader tax and financial strategy.
Your salary affects payroll taxes. It can affect retirement contributions. It influences business expenses and taxable income. And it needs to make sense alongside your distributions, cash flow, and long-term financial goals.
That is a lot of moving pieces.
Which is why we are not fans of making owner compensation decisions based on something someone said in a Facebook group, a YouTube video promising the secret to paying zero taxes, or a friend who insists every S corporation owner should pay themselves exactly $40,000.
Your business is not their business. Your responsibilities are not necessarily their responsibilities. And your financial situation deserves more thought than a one-size-fits-all recommendation.
At Savvion, we believe tax planning, accounting, payroll, and compensation strategy should work together. An appropriate owner salary should be supported by the work you perform, the financial condition of your business, and a tax strategy that considers more than one year’s payroll taxes. Pasted text
That is how you make informed decisions that support both compliance and the long-term health of your business.
There is no single IRS-approved salary amount. Reasonable compensation depends on factors such as the owner’s responsibilities, experience, time devoted to the business, comparable market wages, and the services generating the company’s revenue.
Generally, shareholder-officers who provide substantial services to an S corporation and receive compensation must treat reasonable payment for those services as wages. Different circumstances may apply when an officer performs no services or only minor services and receives or is entitled to no compensation.
Distributions cannot be used to avoid paying reasonable compensation for services. When a shareholder-employee performs substantial work for the business and receives payments, the IRS may require some or all of those payments to be treated as wages.
No. The IRS does not prescribe a universal 50/50 split between wages and distributions. Compensation must be evaluated based on the shareholder’s actual services and circumstances.
A year-end payroll payment may be possible when properly handled, but it must comply with applicable payroll tax withholding, reporting, deposit requirements, and wage payment rules. Regular payroll is generally easier to manage and document.
Yes. The IRS can reclassify distributions or other payments as wages when they represent compensation for services performed by a shareholder-employee.
S corporation income generally passes through to shareholders and is reported on their personal tax returns. Whether a distribution itself is taxable depends on factors including stock basis and the nature of the distribution.
An annual review is a practical starting point. Additional reviews may be appropriate when the owner’s duties, time commitment, financial circumstances, or business operations change significantly. Pasted text
We spend a lot of time encouraging business owners to take care of their employees: pay them competitively, classify them correctly, plan for wage increases, and make sure payroll is accurate.
Business owners need to apply some of that same thoughtfulness to their own compensation.
Paying yourself is not just about moving money from the business account into your personal account. It is about understanding your role, the value of your work, your tax obligations, and the financial future of your business.
Sometimes a reasonable compensation review confirms that you are doing everything correctly. Great. Sometimes it reveals opportunities to make adjustments. Also great, especially when you find them before they become problems.
The goal is not to pay yourself as little as possible, and it is not to pay yourself as much as possible. It is to pay yourself appropriately, document your decisions, and make sure your compensation fits into a thoughtful financial strategy.
After all, you are working hard to build a successful business.
Your paycheck should make sense too.